 5.0 Out Of 250+ Reviews


 Financing Available


 (214) 227-2763

Last Updated: November 7, 2026
Quick Summary
To negotiate a fair storm damage settlement, read your policy limits and deductible first, then document all damage with photos and an itemized inventory. Get at least two licensed contractor estimates and send the insurer a written line-item counteroffer tying each disputed item to evidence.
- Pull your declarations page, coverage sections, exclusions, and endorsements before you call your adjuster.
- Photograph and film all damage and build a dated inventory before any repairs begin.
- Get written line-item bids from at least two licensed contractors to anchor your claim valuation.
- The first check is usually actual cash value, with recoverable depreciation released after completed work.
- Follow up in writing every week and escalate in order: supervisor, appraisal, public adjuster, attorney.
Table of Contents
- Step 1: Review Your Policy and Coverage Limits Before You Negotiate
- Step 2: Document Every Loss With Photos, Videos, and an Itemized Inventory
- Step 3: Get Independent Contractor Estimates to Anchor Your Claim Valuation
- Step 4: Build Your Line-Item Counteroffer and Sample Letter Responding to a Low Settlement Offer
- What Happens When You Reject an Insurance Settlement Offer
- How Long It Takes to Get a Second Settlement Offer and How to Track It
- Negotiating Insurance Settlement for Property Damage: Timeline, Scripts, and Escalation
- Get a Contractor-Backed Storm Damage Settlement Review
- Frequently Asked Questions
Step 1: Review Your Policy and Coverage Limits Before You Negotiate
The most common mistake we see is homeowners starting the negotiation before they read their own policy. Your insurance policy is the rulebook. It states what is covered, what is excluded, and how much the insurer will pay.
Before you call your adjuster, pull out your policy and find these sections:
- Declarations page: Shows your coverage limits and deductible.
- Coverage sections: Lists what property is protected, like the roof, siding, and gutters.
- Exclusions: Names the damage the policy will not pay for.
- Endorsements: Adds or changes coverage, often for wind or hail.
The deductible is your out-of-pocket share. Your coverage limits cap what the insurer pays. Knowing both numbers tells you the real target for your storm damage settlement.
Step 2: Document Every Loss With Photos, Videos, and an Itemized Inventory
Proof wins negotiations. A low offer usually means the adjuster missed damage or valued it too low. Your job is to close that gap with evidence.
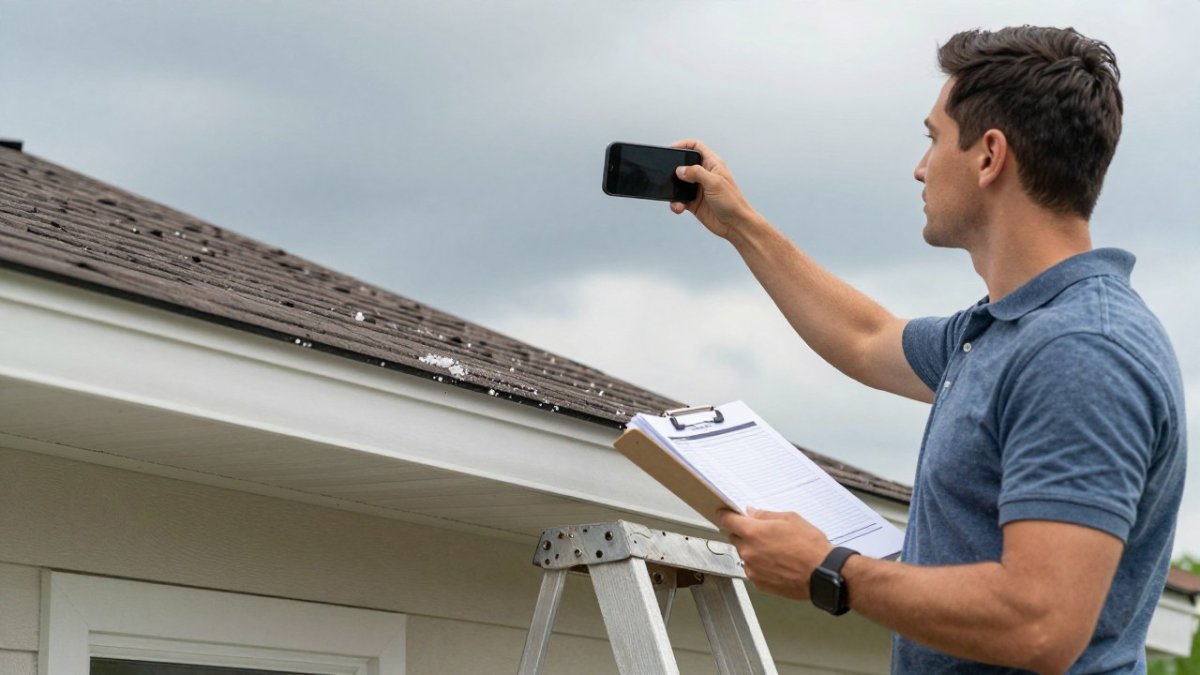
Start before any repairs. Photograph and film everything, from the roof to the gutters to the water stains on your ceiling. Then build a written inventory.
A strong claim file includes:
- Wide photos of each room and each side of the house
- Close-ups of dents, cracks, missing shingles, and rot
- Video walkthroughs with your narration
- A dated list of every damaged item, with age and condition
- Receipts for emergency repairs and out-of-pocket expenses
For a full walkthrough of this process, see our guide on how to document storm damage for insurance. The more complete your supporting documentation, the harder it is for the insurer to justify a low number.
Step 3: Get Independent Contractor Estimates to Anchor Your Claim Valuation
An independent repair estimate gives you a number to negotiate against. The insurer’s adjuster writes one estimate. You should have your own.
Call at least two licensed contractors and ask for written, line-item bids. Each bid should break out materials, labor, and code upgrades. This becomes your contractor estimate and the anchor for your claim valuation.
Compare the contractor bids to the insurer’s repair estimate side by side. Look for:
- Missing line items, like decking or flashing
- Labor priced below local rates
- Actual cash value used where replacement cost applies
- Depreciation taken on items that should be fully covered
If you need help getting credible numbers, our guide on how to get accurate independent repair estimates explains what to ask for.
Step 4: Build Your Line-Item Counteroffer and Sample Letter Responding to a Low Settlement Offer
A counteroffer is your written response to the insurer’s number. Do not argue in general terms. Go line by line, and make the adjuster’s job easy: show the omitted item, show your number, show the evidence.
How to build the line-item comparison
Put the insurer’s estimate and your contractor bids side by side in a spreadsheet. Use the same line-item categories the adjuster uses (roofing, siding, gutters, interior, code items) so nothing gets lost in translation. Then work through four passes:
- Quantity pass. Compare measured quantities. Adjusters often price a partial tear-off or fewer squares than the roof actually requires. Count the same way your contractor did and note the difference.
- Omitted-work pass. List work the insurer’s estimate leaves out entirely, decking, flashing, drip edge, ridge vent, ice-and-water shield, fascia, and interior paint or drywall touched by water. Omitted lines are the easiest to win because the evidence is usually a photo.
- Pricing pass. Compare unit prices for labor and materials against your contractor bids. Regional labor rates and material grades vary, and a low unit price on a large quantity can move the total by thousands.
- Depreciation and code pass. Flag lines where actual cash value was applied but replacement cost coverage applies, and add code-required upgrades (decking attachment, ventilation, permits) that the estimate missed.
The counteroffer table
Build a simple table in your letter. List each disputed item, the insurer’s number, your number, the difference, and the evidence that supports yours.
| Line item | Insurer | Your number | Difference | Evidence |
|---|---|---|---|---|
| Roof decking (sheets) | $0 | $1,850 | $1,850 | Photos 12-18; contractor bid line 4 |
| Gutter replacement | $640 (partial) | $2,400 (full) | $1,760 | Two bids; rust at seams |
| Interior drywall | Excluded | $1,200 | $1,200 | Video 3:10; moisture readings |
Difference
Use your own real numbers from the bids and the estimate, the table above shows the format, not a target. Total the difference column so the adjuster sees one revised figure at the bottom.
Sample letter you can adapt
Dear [Adjuster Name],
Thank you for your estimate dated [date] for claim [number]. After review, we dispute several line items and request a revised offer. A line-item comparison is attached.
Keep every message in written communication. Email creates a paper trail you can use later. To make sure your counteroffer includes everything the insurer expects, review what to include in a supplemental insurance claim.
What Happens When You Reject an Insurance Settlement Offer
Rejecting an offer does not end your claim. It restarts the conversation. The insurer must respond, usually by reviewing your evidence or sending a revised offer.
Here is what typically follows a rejection:
- The adjuster reviews your counteroffer and evidence
- A reinspection may be scheduled
- The insurer issues a revised offer or stands firm
- If talks stall, you move to dispute resolution
Understand what the first check actually represents
Most storm damage policies pay in two stages. The first payment is usually the actual cash value, replacement cost minus depreciation, less your deductible. The withheld depreciation is called recoverable depreciation, and you recover it only after the work is completed and you submit proof, typically invoices, receipts, and photos of the finished job. This is the single most misunderstood part of a settlement: a number that looks low on the first check may be a payment-mechanics issue, not a coverage dispute.
Before you accept or reject, confirm three things in writing:
- Whether the estimate is replacement cost or actual cash value
- The exact recoverable depreciation amount being held back
- The deadline and documentation the insurer requires to release it
Supplemental claims for hidden and delayed damage
Storm damage is often discovered in stages. Once tear-off begins, contractors routinely find rotten decking, cracked flashing, or wet insulation that no one could see from the ground. You do not need a new claim for this, you file a supplement. Document the newly discovered damage with dated photos before it is covered up, get a line-item bid for the added work, and send a written supplement request referencing the original claim number. Check your policy for the exact period that applies to supplemental claims. Check your policy for the exact period.
Temporary repairs, mitigation, and additional living expenses
You have a duty to prevent further damage, and money you spend on reasonable mitigation, tarping a roof, boarding a window, drying a room, is generally reimbursable on top of the repair estimate. Keep every receipt and photograph the before-and-after condition. If the home is uninhabitable, your policy may include additional living expenses coverage for temporary housing, meals, and related costs above your normal spending; that coverage has its own limit and its own documentation requirements, so track it separately from the property damage claim.
Your escalation options
You have options if the insurer will not budge. An appraisal clause in many policies lets both sides hire appraisers, and the two appraisers pick a neutral umpire if they disagree, it is often faster and cheaper than litigation. A public adjuster can represent you for a fee, commonly a percentage of the settlement, so confirm the fee and contract terms before signing. An insurance attorney is the last step before litigation.
If the insurer denies the claim outright, you can appeal. Our guide on why storm damage claims get denied covers the common reasons and the appeal steps.
How Long It Takes to Get a Second Settlement Offer and How to Track It
A second offer usually takes a few weeks, not days. The exact time depends on your insurer, the size of the claim, and whether a reinspection is needed.
Track your claim like a project. Keep a simple log:
| Date | Action | Who | Response Due |
|---|---|---|---|
| Nov 3 | Sent counteroffer | You | 10 business days |
| Nov 14 | Adjuster acknowledged | Insurer | TBD |
| Nov 21 | Reinspection scheduled | Insurer | Nov 30 |
Follow up in writing every week. Ask for a status update and a date. Claim deadlines matter, so note any response windows in your policy. A written log keeps the pressure on and protects you if you later escalate.
Negotiating Insurance Settlement for Property Damage: Timeline, Scripts, and Escalation
Negotiation is a process, not a single call. Here is the timeline we recommend:
- Week 1: File the claim and document all damage.
- Weeks 2-4: Get contractor estimates and review the first offer.
- Week 5: Send your line-item counteroffer.
- Weeks 6-8: Follow up and handle reinspection.
- Week 9+: Escalate to appraisal or a professional if talks stall.
Use short scripts on calls. Try: “I’ve sent a written counteroffer with contractor bids. Can you confirm receipt and a review date?” Then: “If we can’t agree, I’d like to discuss the appraisal clause in my policy.”
Escalate in order: supervisor, appraisal, public adjuster, attorney. For a deeper set of scripts on roof claims, read our guide on how to negotiate a roof insurance claim settlement.
Get a Contractor-Backed Storm Damage Settlement Review
The gap between a low offer and a fair one is usually evidence.
That is where we come in. StormPros is a family-owned general contractor with over 20 years of combined experience. We handle roofing, siding, gutters, and painting, and we act as insurance claim specialists. We are fully insured.
You do not have to accept the first number. Get a free quote and let us review your claim before you sign anything.
If your offer looks low, the next step is simple: gather your photos, your policy, and your contractor bids, then get a second set of eyes on the numbers.
Frequently Asked Questions
When should you not accept a storm damage settlement offer?
Do not accept an offer when the insurer’s estimate omits line items you can document, uses actual cash value where your policy pays replacement cost, or leaves out recoverable depreciation you are owed. Compare the offer against your contractor estimates and your policy’s coverage limits and deductible. If the gap is material and your supporting documentation is solid, a counteroffer is the better move than signing a release.
What should you avoid saying to an insurance adjuster?
Avoid guessing at causes, downplaying damage, or agreeing that a number ‘looks about right’ during the first inspection. Do not say you have no receipts or no contractor estimate if you can gather them. Keep communication written where possible, describe damage factually, and refer questions about scope to your documentation. Statements made early can shape claim valuation long after the adjuster has left.
Should you deposit a settlement check while you are still negotiating?
Treat a check as a potential release. In many policies, cashing a payment labeled as full and final settlement can close the claim, so read the accompanying letter and any release language first. If the payment is partial, such as an initial actual cash value amount, confirm in writing that depositing it does not waive your right to recover depreciation or file a supplemental claim for hidden storm damage.
Can you negotiate a homeowners insurance settlement for storm damage?
Yes. A storm damage settlement is a negotiation, not a final verdict. You can submit a line-item counteroffer, independent contractor estimates, and photos that document missed damage. If talks stall, your policy may include an appraisal clause, and you can escalate to your state’s department of insurance. Persistence with organized supporting documentation is what moves a low initial offer toward a fair settlement.


